Crude prompt steady as IEA highlights rapid inventory draws
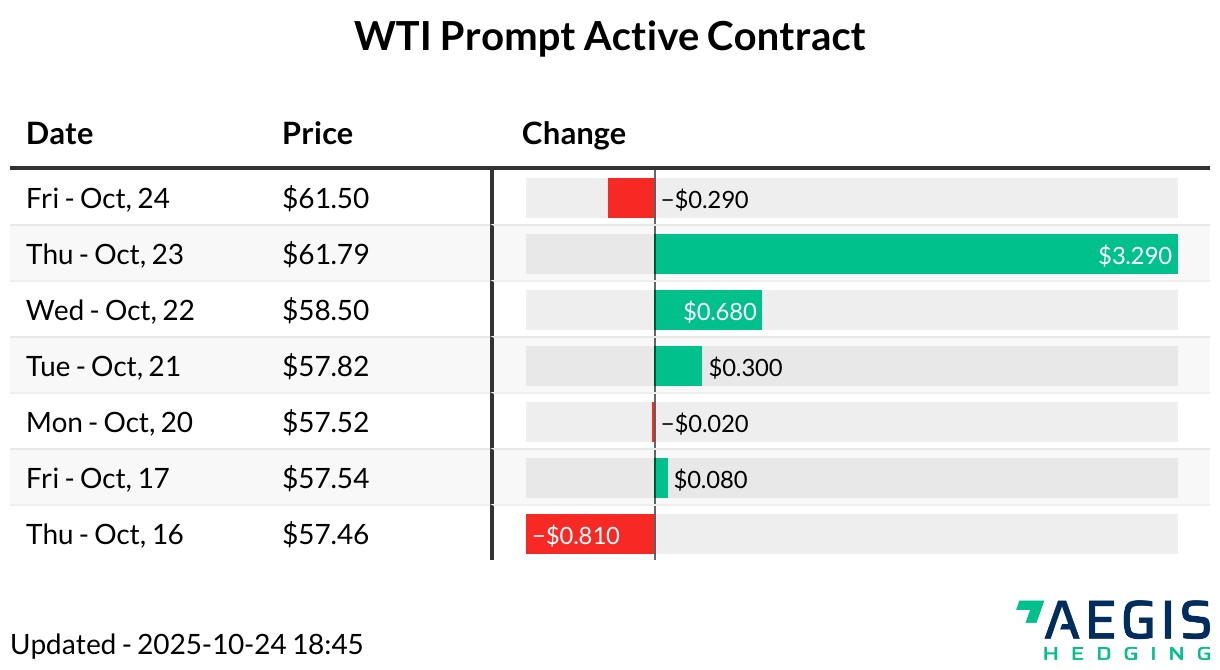
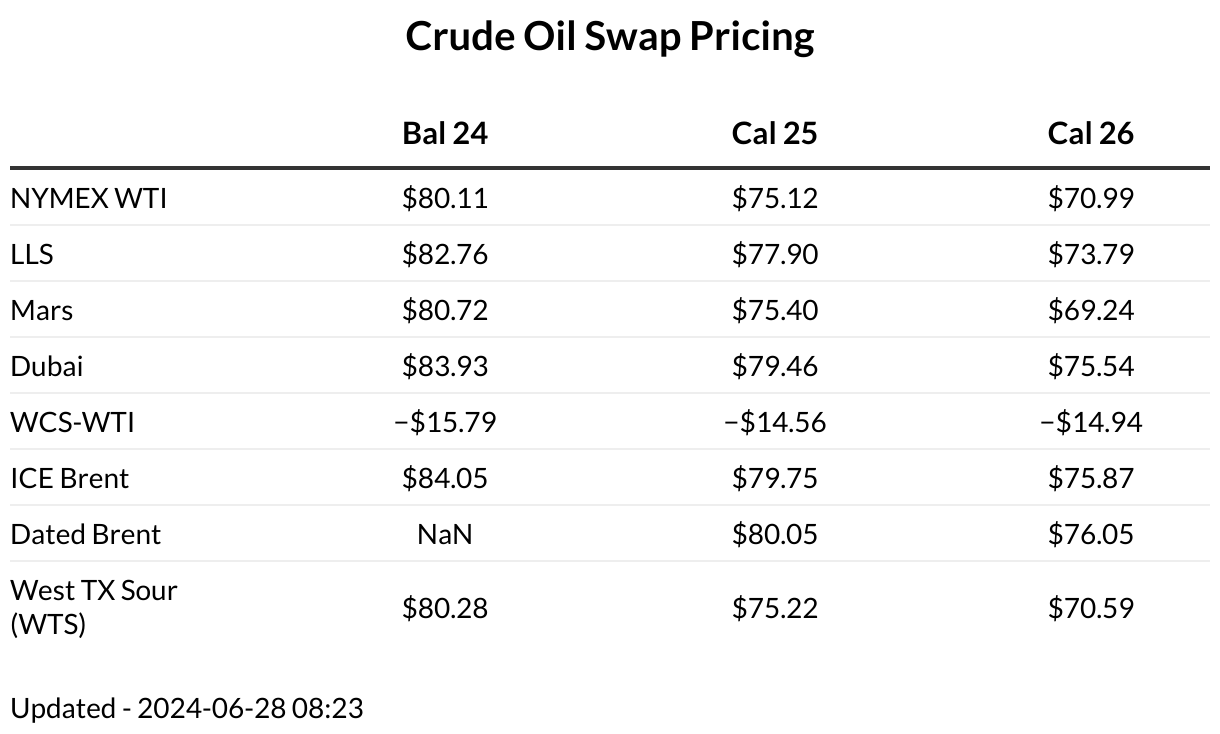
The WTI prompt-month contract gained $0.40 to $102.58/Bbl on Wednesday morning (7:30 AM CT)
Oil futures remained near $102/Bbl after the IEA estimated global observed crude and product inventories fell by roughly 4 MMBbl/d across March and April
The agency warned that even if a diplomatic agreement is reached, restoring crude flows through the Strait of Hormuz could take considerable time
“It could take weeks or even months for transit through the Strait to return to normal levels,” Toril Bosnoi, head of the IEA’s oil markets and industry division, said
The IEA also lowered its global demand outlook for a third consecutive month as elevated prices and disrupted fuel trade continue to pressure consumption
Global oil demand is projected to decline by 2.45 MMBbl/d in 2Q 2026
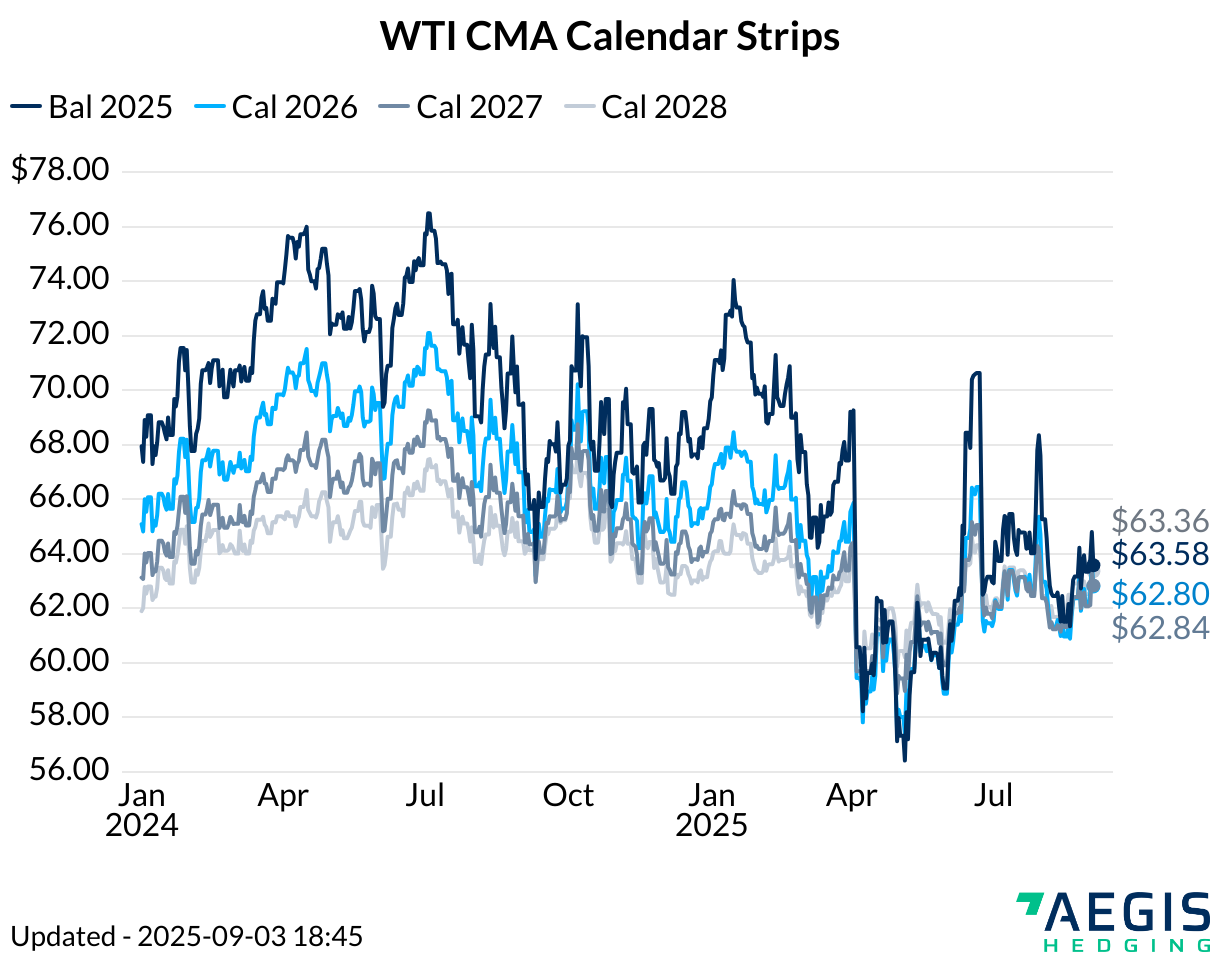
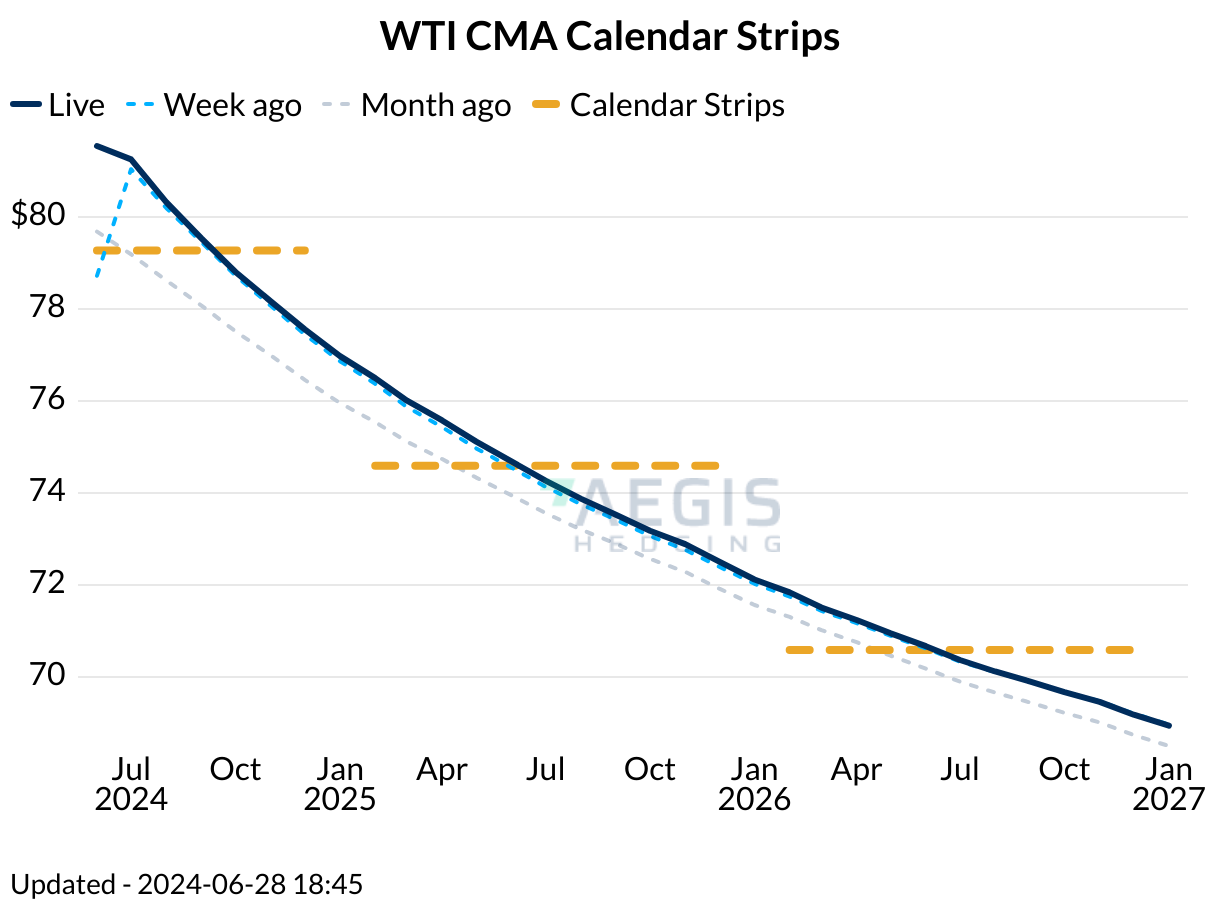
Expectations of weaker global oil consumption may be contributing to a steeper backwardated curve this morning, with deferred contracts under pressure and the Cal 2027 strip falling below $76/Bbl.
Separately, Saudi Arabia told OPEC that its crude production fell to the lowest level since 1990
Natural gas is up as softening supply offsets demand losses
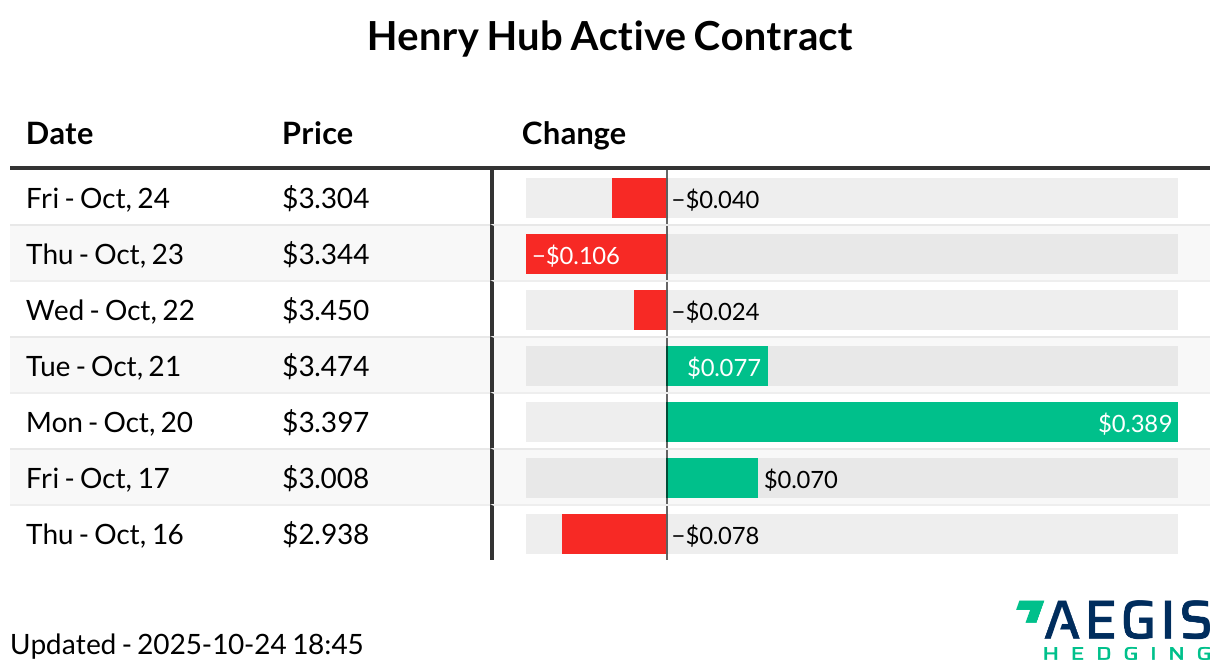
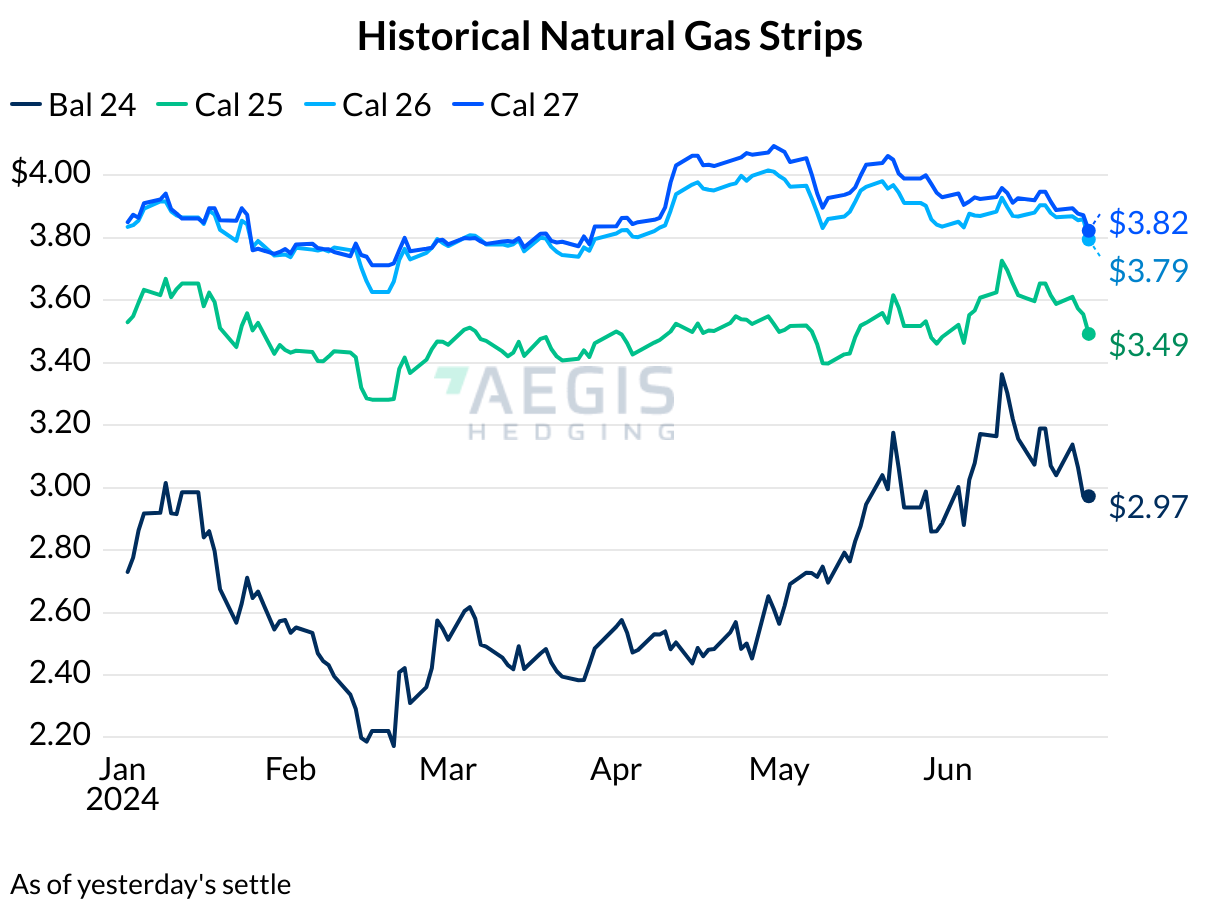
Natural gas is up 5.4c to $2.897/MMBtu (As of 07:43 AM CDT)
Total L48 production slipped to 108.8 Bcf/d, led by losses in the Northeast and GOA
Canadian imports also pulled back 0.3 Bcf/d pulling total supply to 113 Bcf/d, a recent low (Criterion)
The implied net balance came in at a 9.4 Bcf injection, tightening by almost 10 Bcf from earlier in the week (Criterion)
Relatively mild 2026 weather has affected L48 regions storage levels differently
Heading into the summer months the Rockies, Pacific, and South Central regions are all >50% full in storage capacity at 73%, 66%, and 61% respectively as of May 1st (S&P)
East and Midwest storage levels remained lower at 37% and 38% full, potentially increasing summer injection demand in those regions
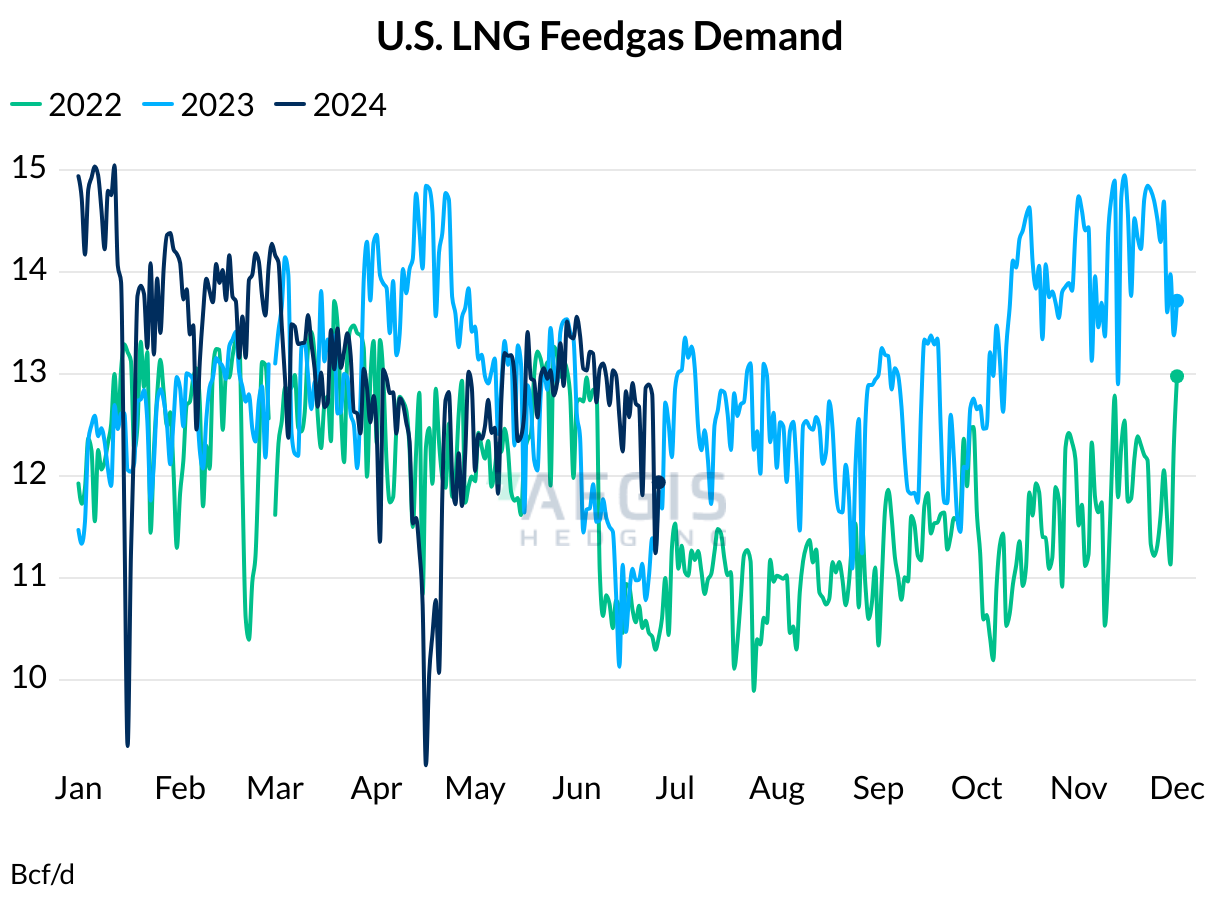
L48 feedgas demand further weakens to 17.5 Bcf/d
Feedgas pulled back 714 MMcf/d this morning to a fresh new low, led by losses at Freeport, Plaquemines, Golden Pass, and Sabine Pass (Criterion)
This is despite a comeback from Corpus, which gained 319 MMcf/d in nominations this morning
Calcasieu Pass 2 construction phase 1 on track for first LNG in 2H27
Venture Global maintained the target start date for the 1.33 Bcf/d facility in its recent earnings call
Get market insights delivered to your Inbox every day!